Cash App Guide: Send Money Safely in 2026
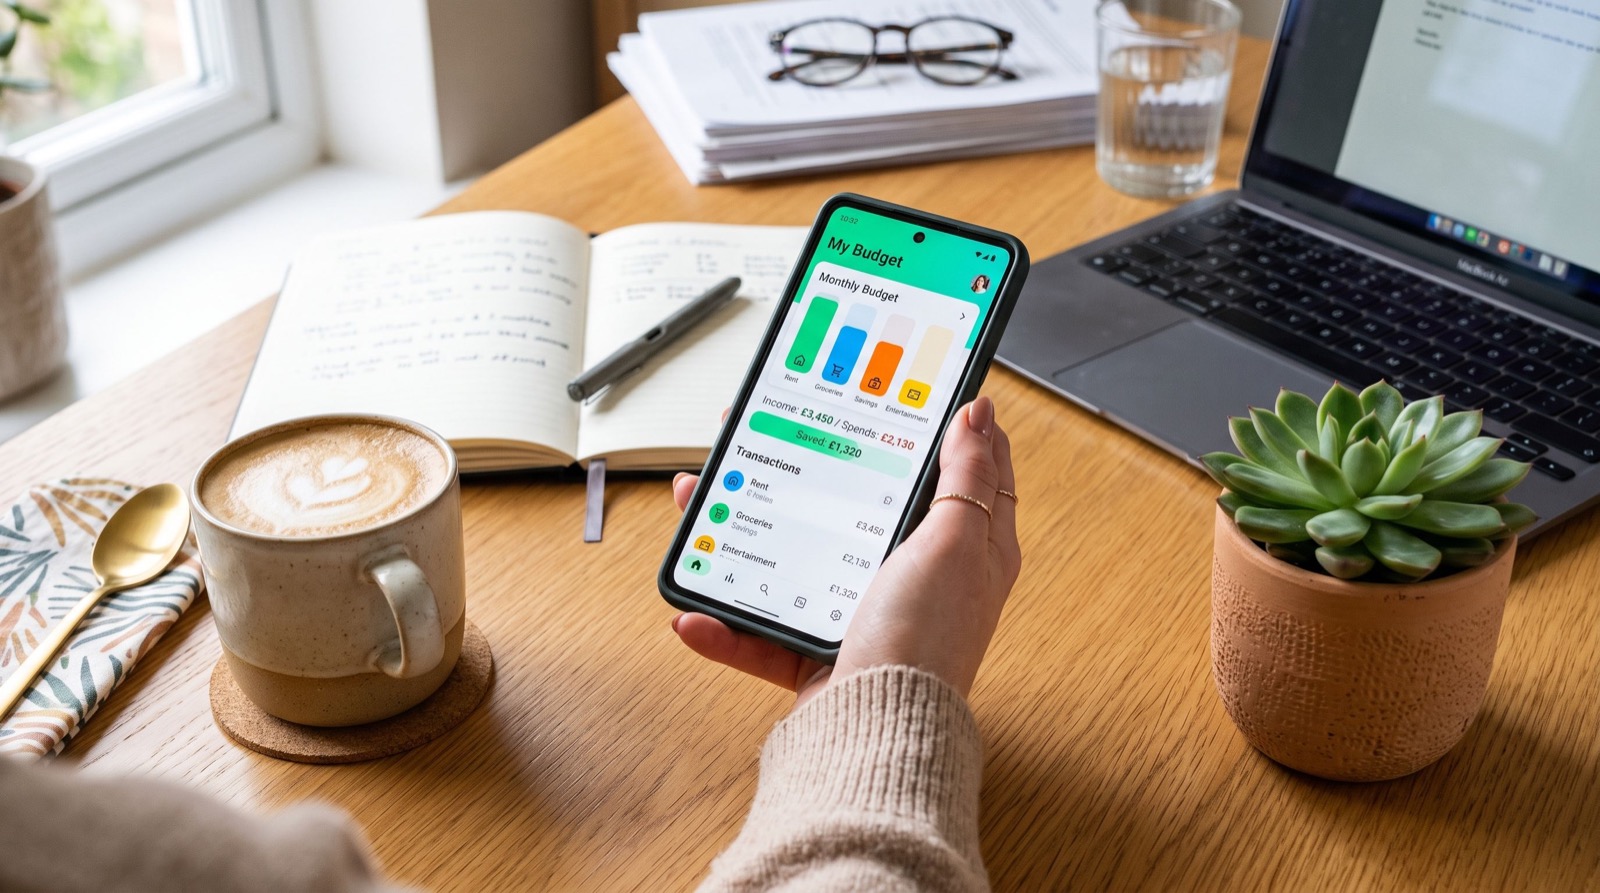
Digital wallets have quietly replaced cash for a whole generation, and this Cash App guide focuses on the part most tutorials ignore: keeping your money secure while you move it. In 2026, instant payments are effortless, but that speed cuts both ways, because a mistaken transfer or a clever scam can drain funds before you notice. Whether you are paying a contractor, splitting a group gift, or running a side hustle, the habits below will protect every dollar you send.
I have used mobile wallets daily for years, and the difference between a smooth experience and a costly one almost always comes down to a few overlooked settings. Let’s fix those first.
Lock Down Your Account Before You Send a Cent
Security is not a feature you add later; it is the foundation of using any payment app well. Spend ten minutes here and you will avoid the vast majority of problems users report.
- Enable a PIN and biometric login so a lost phone does not mean lost money.
- Turn on transaction notifications for instant awareness of any activity.
- Confirm your linked email and phone are current for recovery.
- Never store more than you need in your app balance.
The Federal Trade Commission reports that payment-app scams remain one of the fastest-growing fraud categories, and nearly all of them rely on urgency and impersonation. Slowing down is your strongest defense.
How Does This Cash App Guide Prevent Common Scams?
Scammers evolve, but their playbook is predictable once you know it. Recognizing the pattern lets you shut them down instantly.
The fake support trap
Fraudsters pose as customer support and ask for your PIN or a verification code. Legitimate support will never request these, so treat any such message as an immediate scam regardless of how official it looks.
The overpayment refund trick
Someone “accidentally” sends you money, then begs you to refund it. The original payment is often reversed later, leaving you out of pocket. When in doubt, do not send anything back and contact support through the app directly.
Comparing Digital Wallets in 2026
No single wallet is perfect for everyone. The table below compares common options so you can match a tool to how you actually pay and get paid.
| Wallet type | Strength | Limitation |
|---|---|---|
| Peer-to-peer app | Instant transfers between friends | Few protections for goods and services |
| Bank mobile app | Strong fraud protection | Slower transfers to outside accounts |
| Merchant checkout wallet | Buyer protection on purchases | Not ideal for person-to-person |
| Prepaid card app | Limits exposure to a set balance | Possible reload or ATM fees |
If you are still deciding which tools deserve space on your phone, this shortlist of the best money apps compares features and fees so you can choose with confidence.
Using Payment Apps for a Side Hustle
Freelancers and small sellers increasingly get paid through mobile wallets, and that changes the rules a little. Business use brings tax reporting and higher fraud stakes.
- Keep business and personal transactions separate for clean bookkeeping.
- Save records, since payment platforms report income above certain thresholds to tax authorities.
- Verify large payments clear fully before delivering goods.
- Consider a dedicated business profile where available.
A practical tip from experience
For any transaction with a stranger, screenshot the confirmation and note what it was for. When a dispute or tax question comes up months later, that two-second habit turns a stressful guessing game into a quick lookup. It has saved me more than once.
Master the Features Beyond Basic Transfers
Modern payment apps do far more than move money between friends. Explored fully, they can replace several separate tools.
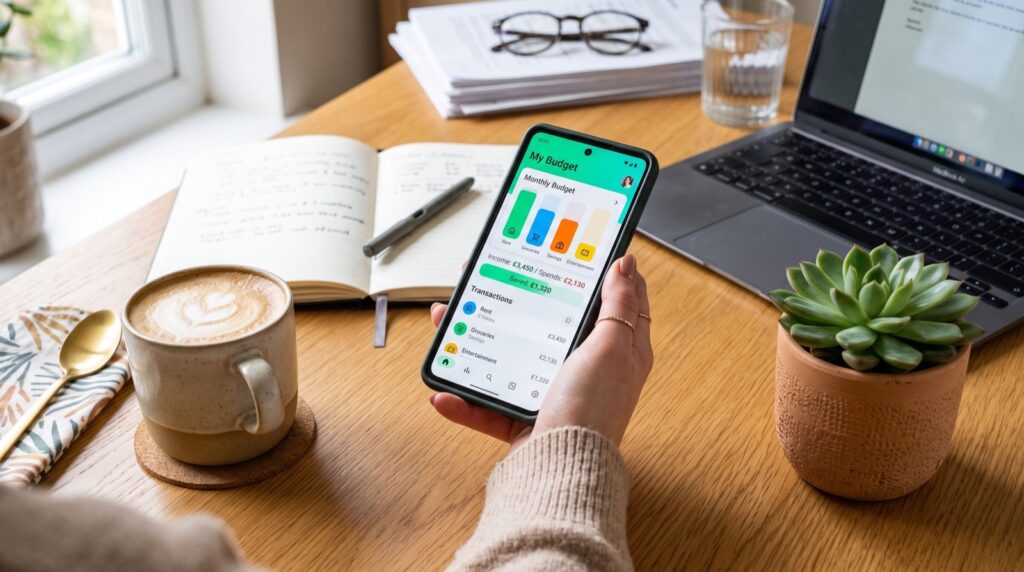
You can often receive direct deposits early, get a linked debit card, and set aside savings inside the same app. If you want a step-by-step reference for enabling each feature safely, this detailed Cash App guide walks through the settings in plain language.
Learning these tools well is a skill worth teaching, especially to teens and older relatives. Pairing hands-on practice with reliable local experts makes the learning stick far faster than trial and error alone.
Teaching Family Members to Pay Safely
Digital wallets are not just for the young. Older relatives increasingly use them to send gifts and split costs, and teens are learning money skills earlier than ever. Both groups are prime targets for fraud, so a little coaching goes a long way.
Start with the golden rule: only send money to people you personally know and trust. Walk them through spotting the classic scams, such as the fake prize and the urgent request from a supposed relative in trouble. Practicing a few transfers together builds confidence quickly.
Set sensible limits for younger users and review their activity together at first. The goal is not surveillance but shared learning, so they build lasting habits rather than dependence.
Build a simple monthly money routine
Security is a habit, not a one-time setup. A short monthly check keeps your account healthy and catches problems while they are still small and fixable.
- Scan your recent transactions for anything unfamiliar.
- Sweep excess balance to your primary bank account.
- Confirm your recovery email and phone are still current.
- Review any recurring payments and cancel what you no longer use.
Ten minutes a month in 2026 is a tiny price for peace of mind, and it turns your payment app from a potential liability into a dependable tool you fully control.
Frequently Asked Questions
How do I send money safely with a payment app?
Only pay people you know, double-check the recipient’s username, and never send money to claim a prize or refund. Enable a PIN and notifications so you catch any unauthorized activity fast.
What should I do if I send money to the wrong person?
Request the money back through the app immediately and contact support if the recipient refuses. Transfers between individuals are hard to reverse, which is why verifying first is so important.
Are payment app balances taxed?
Personal gifts and reimbursements are not income, but money earned for goods or services may be reported to tax authorities above certain thresholds. Keep clear records if you sell or freelance.
Is a bank safer than a payment app?
Both can be safe when used correctly, though banks often offer stronger fraud protections. A smart approach keeps most funds in your bank and only a working balance in your app.
Final Word
This Cash App guide comes down to one principle: move fast on payments, but slow down on security. Lock your account, learn the scam patterns, keep records for any business use, and hold most of your money outside the app. Do that, and mobile payments in 2026 become the convenient, low-stress tool they were meant to be. Set up your safeguards today and send with confidence.